

Bright: Loans & Credit Builder

- 15.21K Reviews
- 4.6
- Downloads
- 1,000,000+
Our take on Bright: Loans & Credit Builder from Appgk
I approached Bright: Loans & Credit Builder as a practical finance app rather than a general budgeting tool. Its central promise is helping people work toward a stronger credit profile while also making loans and credit cards easier to explore. That focus gives it a clearer purpose than many finance apps, but it also means the value depends heavily on your situation, your repayment habits, and what you expect from a credit-building service.
In my experience, the most important thing to understand is that Bright is not a magic shortcut to better credit. It is better viewed as a guided financial assistant for someone who wants to organize borrowing around a longer-term goal. The app is free to install, is aimed at everyone, and comes from Bright Money. It has reached more than a million installs, with a 4.6 average from roughly 165 thousand ratings and about 15 thousand written reviews, so it is clearly being used by a substantial audience.
Bright’s main capability: turning borrowing into a credit-building plan
The strongest idea behind the app is its AI loan assistant approach. Instead of treating a loan search as an isolated transaction, Bright frames borrowing and credit cards as parts of a broader credit-building journey. That distinction matters. A conventional loan marketplace usually emphasizes available offers, while a basic credit-monitoring app may show progress without helping you decide what to do next. Bright sits between those two experiences.
For a user with limited credit history, the appeal is easy to see. Credit can feel circular: lenders want evidence that you can manage credit, but you need access to credit to create that evidence. Bright is designed to help you navigate that problem by bringing loan and credit-card decisions into one place. The useful outcome is not simply finding a product; it is making a more deliberate choice about whether borrowing supports your financial goal.
Best Parts of Bright: Loans & Credit Builder
Things to Keep in Mind About Bright: Loans & Credit Builder
I would not use the app with the mindset that approval is guaranteed or that every recommendation will be suitable. Financial products are personal, and an option that helps one person may create unnecessary cost or pressure for another. The app can make the decision process more approachable, but it cannot replace checking repayment terms, understanding fees, and deciding whether the monthly obligation fits comfortably into your budget.
That is the first non-obvious trade-off: convenience can make borrowing feel less intimidating, but it can also make it feel easier than it really is. I found the app most useful when treated as a planning layer, not as a reason to take out credit immediately. If your main goal is simply to track spending, build a household budget, or manage investments, a dedicated budgeting or investing app may be a better match.
News and Features Related to Bright: Loans & Credit Builder

News
YouTube Turns a Quick Video Check Into an Hour of Watching

News
BeautyPlus Makes Portrait Retouching Feel Like Your Own

News
TikTok’s Effortless Feed Makes Every Swipe Count—and Every Mistake Harder to Undo
What the AI assistant changes for an ordinary user
The AI angle is most helpful when you have a vague question rather than a precise one. Someone might know that their credit history needs work but not know whether a loan, a credit card, or waiting and improving repayment habits is the sensible next step. An assistant-style experience can make that starting point less confusing than searching through unrelated financial websites.
Still, I would keep a skeptical eye on any suggestion. A recommendation is not automatically a good deal, and a product that appears accessible may still be expensive over time. My practical advice is to write down the total amount you would repay, not only the amount you receive or the minimum monthly payment. That simple habit helps prevent the app’s convenience from becoming a costly impulse.
Don't want to read the full review?
How the experience works in practice
Bright is a finance app, so the quality of the experience depends less on flashy presentation and more on whether it helps you make a calm, informed decision. I would begin by defining one goal before exploring the available credit options. For example, you might want to establish a consistent repayment record, reduce dependence on high-cost borrowing, or understand which type of credit is realistic for your profile.
That goal-first approach is important because the app covers more than one financial need. Its store summary presents it as a way to build credit, get loans, and get credit cards. Those are related but not identical tasks. A person looking for emergency cash has a different priority from someone trying to establish a credit history, and someone comparing cards needs to focus on conditions rather than simply access.
Screenshots
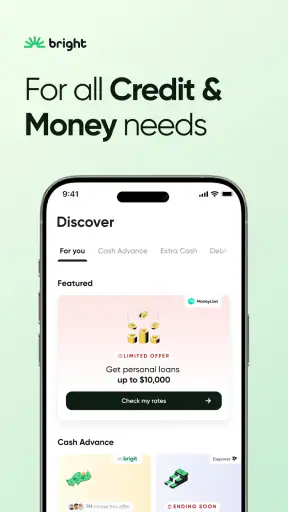
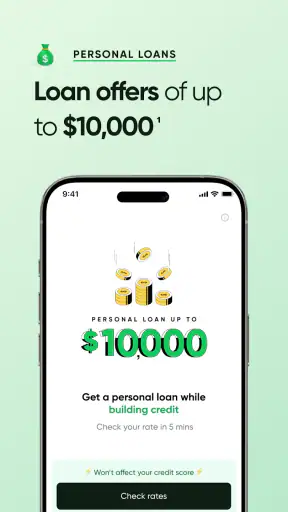
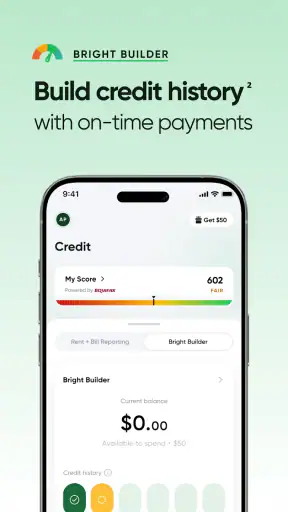
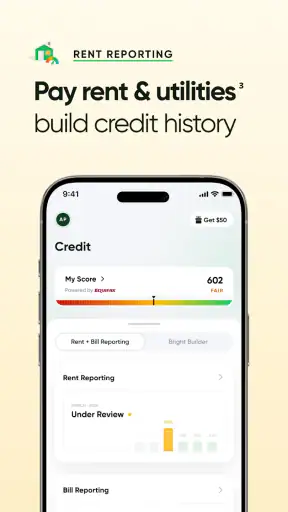
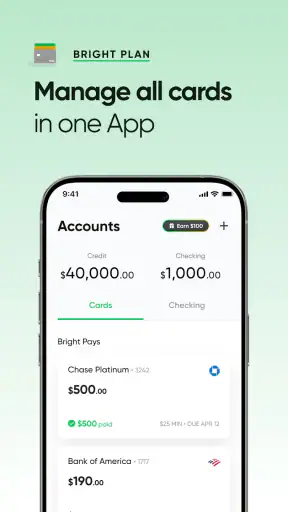
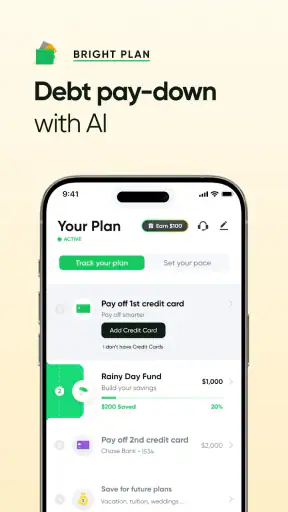
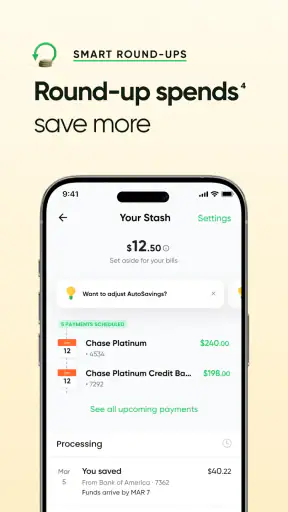
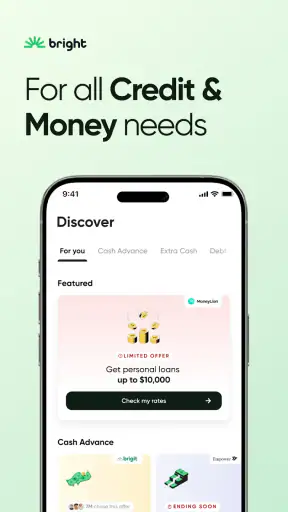
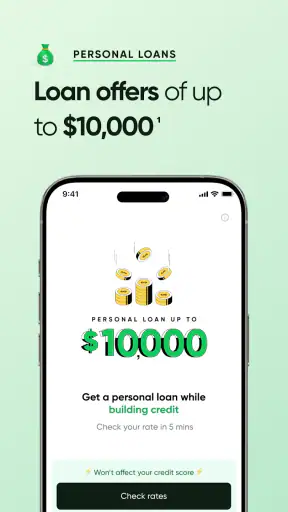
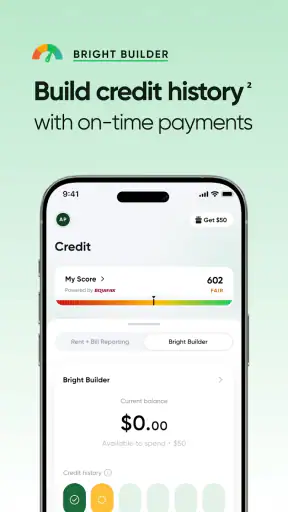
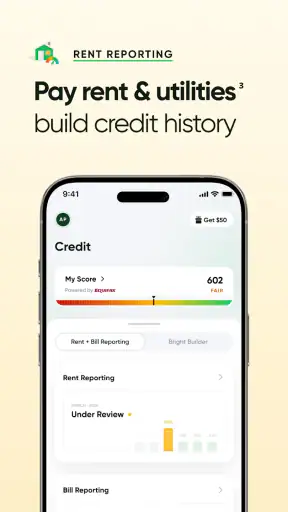
I would also prepare basic information before using the assistant. Have a clear picture of your monthly income, fixed bills, existing debt payments, and the amount you could repay without cutting essentials. This makes any result more useful because you can judge it against your actual life. Without that preparation, it is easy to focus on what you may qualify for instead of what you can responsibly afford.
One useful workflow is to use Bright in two passes. On the first pass, explore the options and note what seems relevant. On the second, return only after checking your budget and considering the full repayment burden. Separating discovery from commitment is a small but valuable discipline, especially when the app makes financial information feel more accessible.
The current version is 1.61.1, and the app supports devices running Android 8.0 or later. That makes it usable on many older Android phones, which is helpful for people who do not upgrade frequently. I would still keep the app updated when possible because finance tools handle sensitive decisions and a current version is generally preferable for stability and maintenance.
Bright is free to install, but that should not be confused with every financial product being free. The app’s download price and the cost of a loan or card are separate questions. Before accepting anything, I would inspect the terms shown for that product, including repayment expectations and any charges. This is one of the most important details a new user might overlook when seeing a free finance app.
A realistic everyday scenario
Imagine someone who has recently moved, has a thin credit file, and needs to replace a broken appliance. They may be tempted to accept the first loan offer that appears because the expense feels urgent. A more careful use of Bright would be to enter with a fixed maximum monthly payment, compare the available path with waiting or using savings, and consider whether the borrowing would improve their situation or simply postpone the problem.
In that scenario, the app’s real benefit is structure. It can help the person think about credit-building and borrowing together instead of treating the loan as free money. If the repayment would leave no room for rent, food, transport, or an unexpected bill, the right conclusion may be not to proceed. That is a successful use of the app even though it does not end with a loan.
Another practical scenario is a user who has a credit card but pays inconsistently. Bright may be more useful as a prompt to approach credit deliberately than as a search for another account. Adding new credit while existing payments are unstable can make the situation harder. I would first focus on reliable payments and only then consider whether another product has a clear purpose.
Where it is more useful than usual alternatives
Compared with visiting several lender websites, Bright offers a more focused starting point for someone who wants to connect a borrowing decision with credit-building. That can save time and reduce the confusion of moving between different application flows. It is particularly approachable for people who do not know the vocabulary of credit products and want a guided place to begin.
Compared with a standard credit-monitoring service, its emphasis is more action-oriented. Monitoring can tell you what has happened, while Bright is designed around what you might do next through loans or credit cards. That is a meaningful difference for users who feel stuck and want a path forward rather than another score screen.
On the other hand, a traditional bank or credit union may be preferable if you already have a trusted relationship, want face-to-face support, or need advice that takes your complete financial picture into account. A nonprofit credit counselor may be a better choice if debt is already difficult to manage. And a simple spreadsheet can be superior if your only need is tracking bills without being exposed to additional borrowing choices.
Trade-offs I noticed before recommending it
The biggest limitation is built into the app’s purpose: it makes credit products central. That is useful when you genuinely need help understanding borrowing, but it is not ideal for someone who should avoid new debt. If you are already missing payments, relying on one card to pay another, or using loans for routine expenses, I would not make Bright your first step. Stabilizing cash flow and seeking independent debt guidance should come before exploring more credit.
A second limitation is that a guided recommendation can never capture every personal detail. Your housing costs, job stability, family responsibilities, existing obligations, and emergency savings all affect whether a product is sensible. The app may help organize the search, but you remain responsible for reading the offer and deciding whether the repayment plan is realistic.
There is also a psychological trade-off. Seeing loans and cards presented alongside credit-building can make borrowing seem like the natural solution to a credit problem. Sometimes the strongest credit-building move is simply paying current accounts on time, reducing balances, and avoiding unnecessary applications. I would use Bright to improve judgment, not to create a reason to apply.
Privacy and trust deserve attention with any finance app. I would review the information requested during setup and only provide what is needed for the feature I intend to use. I would also avoid using the app on a shared or unsecured device, protect the phone with a lock, and sign out when appropriate. These are sensible habits because financial decisions and personal details should not be treated casually.
The app’s age rating is Everyone, which makes its presentation broadly accessible, but that does not mean every financial product inside it is appropriate for every person. A young or inexperienced user may understand the interface without fully understanding interest, repayment risk, or the consequences of missed payments. If you are helping someone else use it, I would discuss the financial commitment with them rather than letting the app make the decision feel automatic.
Three habits that make the app more useful
- Set a repayment ceiling first. Decide the largest monthly amount you could manage after essential bills, then judge every option against that ceiling rather than starting with the amount offered.
- Use the assistant for comparison, not permission. Treat its guidance as a shortlist or explanation, and independently check the full terms before accepting anything.
- Return to the original goal. If the goal is credit-building, ask whether the new account or loan supports consistent payments. If it only adds another bill, it may be moving you backward.
These habits reveal a subtle strength of Bright: it can be valuable even when the final decision is to wait. A finance app should not be judged only by how quickly it leads to a product. Helping someone recognize that borrowing does not fit their budget is a useful outcome, especially when the alternative is an impulsive application.
Who gains the most from Bright
I think Bright is best suited to adults who are new to credit, have a limited credit history, or feel overwhelmed by the difference between loans and credit cards. The guided approach can give those users a clearer starting point than a scattered web search. It is also useful for someone who wants to connect a credit-building objective with a concrete financial decision instead of treating the two as unrelated.
It may also suit a person who is comfortable using a mobile finance tool but wants more direction than a basic score tracker provides. The app’s combination of credit-building guidance and access to borrowing-related options gives it a distinct role. It is not merely a dashboard, and it is not only a lender search; its value comes from putting those ideas in the same conversation.
I would recommend skipping it if you are looking for detailed expense categorization, investment research, tax preparation, or comprehensive debt counseling. Those needs call for different tools and, in some cases, human support. I would also skip it if you are likely to interpret every suggestion as an endorsement or if you are currently struggling to make existing payments.
Bright Money, the developer, has built an app with a clear audience rather than trying to cover every part of personal finance. That focus is a strength, but it narrows the recommendation. The app is most convincing when your question is, “How can I approach credit more deliberately?” It is much less compelling when your question is, “How do I manage my entire financial life in one place?”
After using it as a credit-planning companion, my opinion is positive but careful. The app makes a confusing subject easier to approach and gives credit-building more context than a simple score display. Its free installation and broad device support lower the barrier to trying it, while the large user base suggests it has found an audience.
My final advice is to install Bright only with a specific purpose and a written budget beside you. Explore the guidance, compare the alternatives, and read the repayment details before making any commitment. The app is most valuable when it helps you make a slower, better decision—not when it encourages you to borrow faster. For a newcomer who wants structured help with credit, it is worth considering; for someone already under debt pressure or seeking full financial management, a different kind of support will be the wiser choice.
Bright: Loans & Credit Builder FAQ
What is Bright: Loans & Credit Builder, and how does it work?
Bright is a personal finance app designed to help users manage debt, build credit, and organize repayments. Depending on eligibility and location, it may connect you with lending or credit-building products, while also offering budgeting tools and payment scheduling. Features, rates, approval decisions, and available services can vary, so review the terms shown in the app before accepting any offer.
Can Bright guarantee approval or improve my credit score?
No. Bright cannot guarantee approval for a loan or credit-building product, and using the app does not automatically increase your credit score. Credit results depend on factors such as your payment history, existing debts, account age, and information reported to credit bureaus. Making payments on time may help, but late or missed payments, fees, or new applications could have a negative effect.
How much does Bright cost, and are there additional fees?
Bright may charge subscription, membership, financing, or other service-related fees depending on the product and plan you choose. The exact cost can differ by user, state, eligibility, and promotional terms. Before proceeding, carefully check the pricing page, annual percentage rate, repayment schedule, late-payment consequences, and cancellation conditions. Do not assume that a free download means every feature is free.
Is Bright safe to use with my financial information?
Bright may request personal, banking, income, and credit information to provide budgeting, debt-management, eligibility, or credit-building services. Before linking an account, review the app’s privacy policy, security explanations, data-sharing practices, and permissions. Use a strong password, enable available security protections, and avoid entering sensitive information through unofficial websites or modified versions of the application.
What should I check before downloading and using Bright?
Before downloading Bright, confirm that the app is available in your country and that you meet its age, residency, income, and account requirements. Read the current user agreement and product disclosures, especially information about fees, automatic payments, credit reporting, cancellation, and customer support. Also verify the developer name and download the application only from the official Google Play Store or Apple App Store.











